
The Payment Plan Trap: Financial ‘Hack’ or Liquidity Nightmare?
· 2 min read
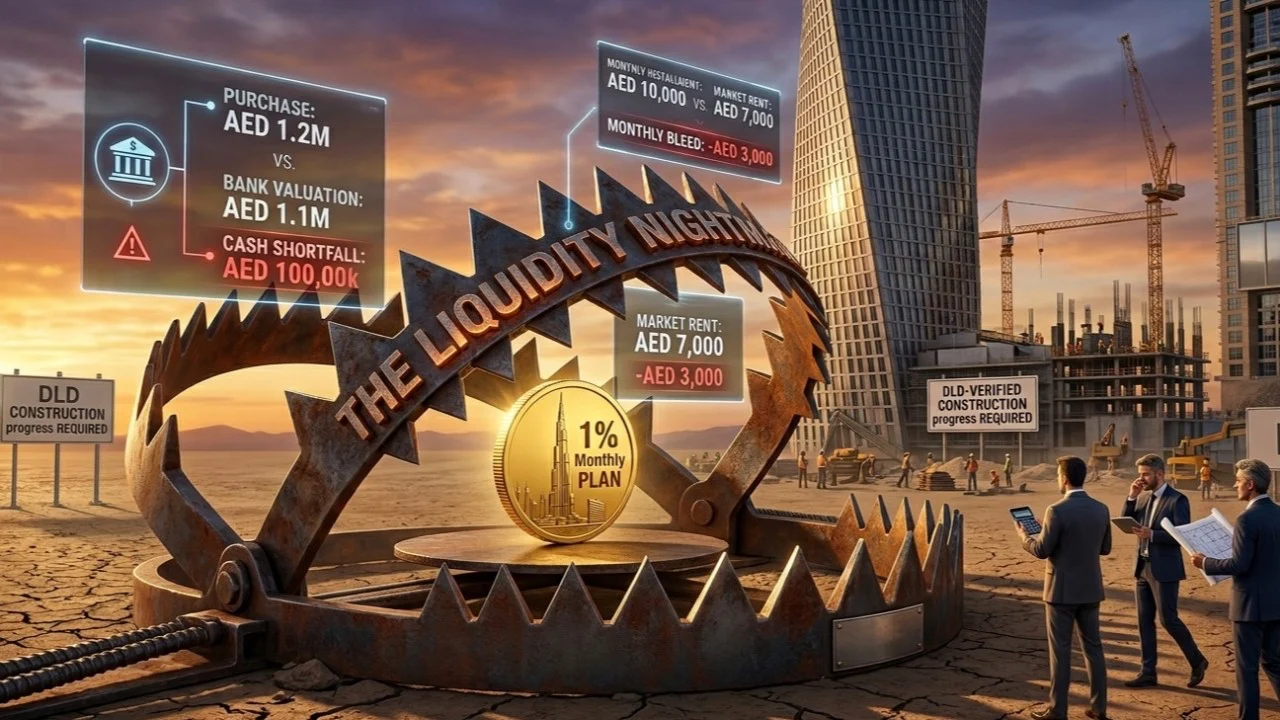
In 2026, the “1% Monthly Plan” has become the gold standard for Dubai’s mid-market, while luxury developers are offering post-handover windows of up to 8 years. On paper, it’s the ultimate financial hack: move in (or rent it out) while still paying off the principal.
But for the unprepared investor, these flexible structures can quickly turn into a “Liquidity Trap”.
The 2026 Reality Check:
- The Valuation Gap: This is the silent killer. In 2026, banks are conservative. If you bought a unit on a 1% plan for AED 1.2M, but the bank values it at AED 1.1M at handover, they will only lend you 80% of their valuation—not your purchase price. You are suddenly liable for the AED 100,000 shortfall in cash.
- The “Yield Myth”: Many investors assume the rent will cover the post-handover installments. The Math: If your monthly installment is AED 10,000 but the market rent is AED 7,000, you are “bleeding” AED 3,000 every month. A payment plan is a commitment, not a guaranteed self-funding asset.
- The Resale Barrier: Most developers in 2026 require you to have paid 30% to 40% of the total value before they will issue an NOC for resale. If you bought with a low down payment and need a quick exit, you might find your capital locked until you hit that threshold.
A post-handover plan is a powerful tool if you have the liquidity to bridge the valuation gap. We advise our clients to treat these plans as a secondary financing option, not a substitute for capital. The “Elite” move is to choose plans where the milestone payments are linked to DLD-verified construction progress, ensuring your money only moves when the building does.
Don’t let a “1% per month” headline distract you from the 100% liability. If the math doesn’t work at handover, it doesn’t work at all.
Want to align your portfolio with institutional data? Contact MODE Properties today for a private consultation on high-yielding Dubai assets.
WhatsApp: +971 56 966 5698 Email: contact@modeproperties.ae
Digital Office: modeproperties.ae/contact LinkedIn: MODE Properties
#dubairealestate #marketintelligence #propertyinvestment #modeproperties #realestate2026
Frequently asked questions
Off-plan means buying a property before it is completed — at pre-launch or during construction. Launch prices are often 20–30% below comparable ready stock, and payment is spread across a construction-linked plan rather than paid up front.
Down payments are typically 10–20% of the property value, followed by construction-linked instalments. Many projects also offer post-handover plans where instalments continue after you receive the keys.
Yes. Dubai's escrow law (Law No. 8 of 2007) ring-fences buyer funds in a regulated escrow account. Money is released to the developer only against verified construction milestones.
Off-plan is simpler than a secondary purchase: the transaction completes immediately on payment of the booking amount, the DLD fee is 4% (developers frequently run promotions where this is waived), and the developer admin fee is variable but typically under AED 5,000.
Yes — with a larger deposit, typically 25–50%, at selected banks. Non-resident loan-to-value is usually in the 50–75% range depending on the bank and your nationality.
Yes — typically after 30–50% of construction is complete, with certain banks on construction-linked terms. Loan-to-value can reach around 70%, though this varies bank to bank. Many buyers use the developer payment plan instead.
Passport or Emirates ID, proof of income (salary certificate or audited accounts), bank statements — usually six months — and details of any existing liabilities. Requirements differ case to case.
For properties under AED 5M: UAE nationals up to 85%, resident expats up to 80%, non-residents typically 50–75%. Above AED 5M the limits step down. Your total monthly obligations are also capped at 50% of income under the Debt Burden Ratio rule.
Around 60 days. We strongly recommend securing pre-approval before you make an offer — it strengthens your negotiating position and removes financing risk from the deal.
Want this applied to your own position?
Free consultation with a specialist advisor — by phone, WhatsApp, video or in person.
 WhatsApp